Date & Time: Wednesday, November 11, 2026, 16:00 KST
Attendees: Co-CEO Byung-moo Park, CFO Won-june Hong
Topic: NCSoft Q3 2026 Financial Results and Future Strategy
■ NCSoft Q3 2026 Financial Results & Status Summary
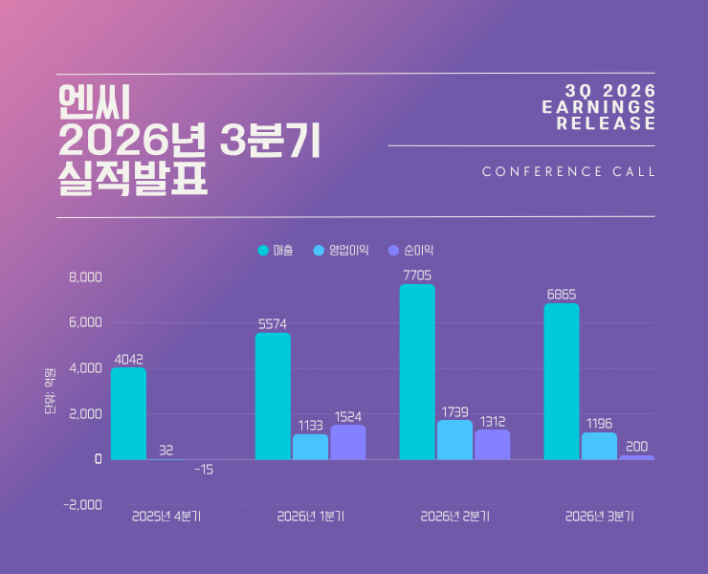
▣ Q3 2026 Financial Highlights
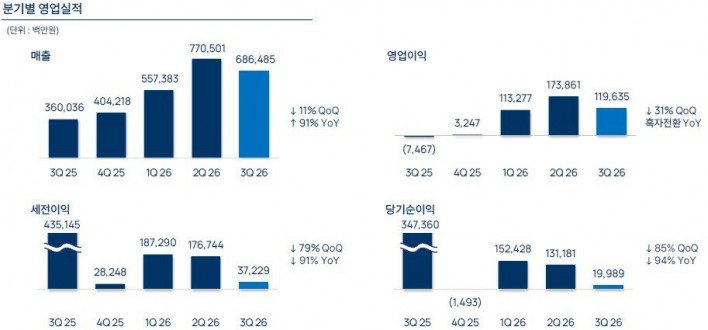
- Q3 2026 revenue of 686.5 billion won (+91% YoY, -11% QoQ)
- Operating profit of 119.6 billion won (turned profitable YoY, -31% QoQ)
- Pre-tax profit of 37.2 billion won (-91% YoY, -79% QoQ)
- Net profit of 20.0 billion won (-94% YoY, -85% QoQ)
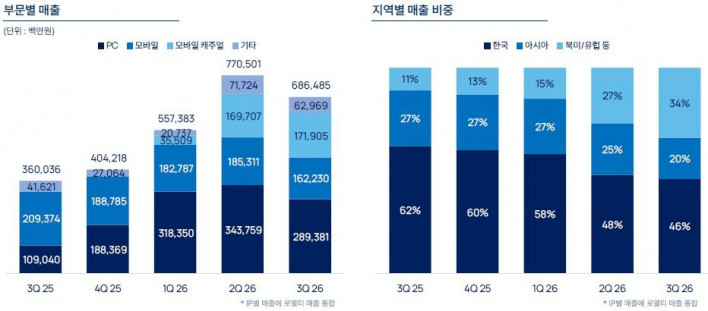
- Mobile revenue of 162.2 billion won
- PC revenue of 289.4 billion won, down 16% QoQ
└ Up 165% YoY
- Mobile Casual revenue of 171.9 billion won
└ Accounted for 25% of total company quarterly revenue
└ Driven by user growth and advertiser demand at JustPlay
- Revenue breakdown by region: Korea 46%, Asia 20%, North America/Europe 34%
└ Overseas revenue share stood at 54%
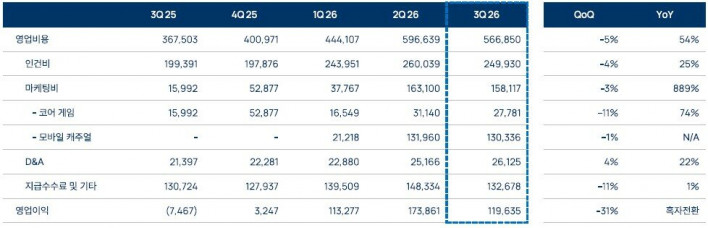
▣ Q3 2026 Expense Breakdown
- Q3 2026 operating expenses of 566.9 billion won (+54% YoY, -5% QoQ)
└ Labor costs: 249.9 billion won (+25% YoY, -4% QoQ)
└ Marketing expenses: 158.1 billion won (+889% YoY, -3% QoQ)
└ Depreciation & amortization: 26.1 billion won (+22% YoY, +4% QoQ)
└ Commission fees and other expenses: 132.7 billion won (+1% YoY, -11% QoQ)
▣ Remarks by Co-CEO Byung-moo Park
2026 can be characterized as a year in which our three main growth pillars established their foundations and yielded tangible results. First, in Q1, we demonstrated successful launches of both existing and new IP in Korea and Taiwan. In Q2, we showed the results of acquiring JustPlay—the central pillar of our Mobile Casual Division—and in Q3, we successfully showcased self-publishing globally for a new IP, Aion 2.
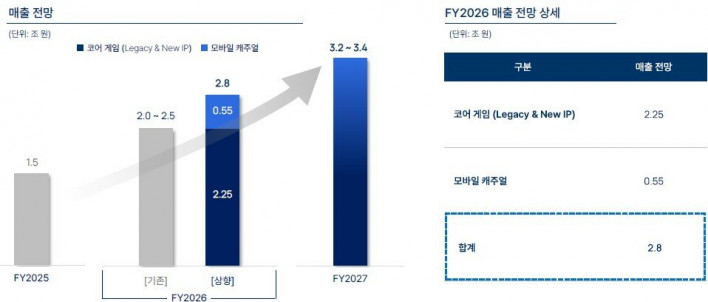
Last year, we provided guidance for this year's revenue at 2.0 to 2.5 trillion won, but based on current trends, we expect to significantly exceed this guidance and reach 2.8 trillion won in annual revenue. Compared to 2025 revenue in the 1.5 trillion won range, this represents remarkable growth, which was made possible thanks to the support and advice of our customers and shareholders, as well as the dedicated efforts of our executives and employees.
Next year, in 2027, we expect continuous growth as these three growth pillars become fully established and refined. Accordingly, we have announced revenue guidance of 3.2 to 3.4 trillion won for 2027. Despite setting this guidance, we will make every effort to exceed it, just as we did this year.
To provide visibility into these forecasts, there are three key areas to keep an eye on. For existing IP, we will continuously pursue the refinement of live services, while maintaining solid revenue through regional expansions, market entries into new territories, and spin-offs—such as the global launch of Aion Mobile, the China launch of Lineage Mobile, and the release of Mistbound utilizing the Guild Wars IP.
For new IP, as already demonstrated with Aion 2, we will further refine our established global publishing capabilities. As a result of improvements made through user testing, new titles in the shooter and subculture genres—including Astraea Oratio, Cinder City, Limit Zero Breakers, and Time Takers—will be launched sequentially throughout the first half of next year.
Regarding the Mobile Casual segment, through additional acquisitions and business expansion in Q4, we expect the framework for reward platforms and publishing services in mobile casual to be largely completed. Starting next year, we will advance these synergies to achieve quantum growth.
Lastly, while we are expanding the application of AI capabilities to game development to match the rapidly evolving AI landscape, I want to emphasize that the business structure transformation NCSoft is pursuing is being optimized for and aligned with this shifting AI paradigm. First, MMO games—our core competitive strength—are considered a field that will be difficult for AI to replace for a considerable period due to their vast game content, sophisticated server technology, and continuous live service operations, so we will continue to develop and refine them.
Furthermore, given the current reality where countless games are being developed using AI, strengthening publishing capabilities is becoming increasingly crucial. To this end, reinforcing global publishing capabilities for co-op games and transforming the mobile casual segment into a publishing platform represent business structures that can deliver sustainable growth under the AI environment.
Although today's presentation focused primarily on 2027 guidance, building on the optimization of NCSoft's business structure, we expect another wave of explosive growth in 2028 when major flagship IPs see full-year contributions and the Mobile Casual Division structure is fully established. We will continue to communicate further details through future media events and disclosures.
■ Q&A
Following the global launch of Aion 2, objective external metrics mostly point to Steam traffic, which shows trends similar to TL's global launch. Retention does not seem noticeably better. Do you see this as a limitation of MMORPGs, or is it a business model (BM) issue?
Co-CEO Byung-moo Park: Overall, K-MMORPGs have a vertical progression structure, so we acknowledge that user churn trends tend to look similar. However, there is a difference in market environment compared to TL. When TL launched, there were few competing titles, whereas Aion 2 launched amidst continuous releases of major competitors like Call of Duty, Phantom Blade Zero, and World of Warcraft Forever. We'd like to emphasize that these results were achieved under those conditions.
Furthermore, comparing TL and Aion 2, retention rates among paying users and hardcore players are significantly higher in Aion 2 than in TL. We are continuously monitoring this, and we would appreciate it if you could continue observing performance through November and December.
The growth momentum in mobile casual looks very strong. What is driving this high growth? How much is mobile casual reflected in next year's guidance?
Co-CEO Byung-moo Park: JustPlay's continuous explosive growth can be viewed from two angles. First, macro-wise, platforms are currently driving game development significantly. Last year, around 2,000 mobile casual games were launched per month, but this year that figure has reached 4,000 to 5,000. This macro shift provides a strong backdrop for reward apps like JustPlay to achieve sustained growth alongside industry expansion.
On a micro level, the team consists of talent highly specialized in AppLovin's adtech. They design user-friendly products that drive higher User Acquisition (UA) and grow Monthly Active Users (MAU). Consequently, advertisers participate by paying higher ad rates, creating a virtuous cycle that continues to expand.
This virtuous cycle is well established micro-wise, and we expect it to sustain ongoing growth. Finally, combined revenue from reward apps as well as publishing and mobile casual game studios is expected to account for roughly 25% to 30% of next year's guidance.
CFO Won-june Hong: Inorganic growth is not included. Any additional revenue and growth stemming from newly announced M&A transactions are not reflected in this guidance.
Are there plans for UI/UX updates in mobile casual? Could you also provide an update on JustPlay's key metrics?
Co-CEO Byung-moo Park: JustPlay's primary markets currently are North America and parts of Europe. We noticed the JustPlay app recently appeared in Korea, but that is a beta service rather than an official launch. When we officially expand into the Korean market in the future, we will naturally address any areas that require improvement.
As mentioned earlier, additional M&A and business expansion will complete the framework we envision. This includes plans to expand reward apps into 3P and IAP domains. Once expanded into 3P and IAP, the triangular synergy among studios, publishing, and reward apps will be significantly enhanced beyond the existing 1P model.
CFO Won-june Hong: One of the core mobile casual strategies envisioned by our co-CEOs is the ongoing pursuit of additional M&A. JustPlay focuses on IAA and 1P, whereas the additional ventures currently pursued focus on IAP and 3P. The strategy is to establish a complete ecosystem through complementary synergies.
Detailed metrics for JustPlay pertain to core competitive capabilities, so we cannot disclose specific numbers. However, MAU has roughly doubled compared to last year. Looking at current trends, we expect 2027 revenue to grow by at least 50% or more over this year's expected annual revenue. We feel confident based on current indicators.
What is the marketing expense guidance for 2027?
CFO Won-june Hong: We executed marketing expenses very efficiently this year. Over the past three years, we have operated marketing spend efficiently, and with the introduction of ROAS concepts in mobile casual, management has become even more systematic.
As we have consistently stated, we strictly adhere to the principle of maintaining marketing expenses below 10% of total revenue. Next year, despite multiple new game launches, we expect marketing spend to remain meaningfully below 10% of total revenue.
What are the plans for Horizon Steel Frontiers?
Co-CEO Byung-moo Park: Horizon Steel Frontiers is nearing completion, and we are continuously discussing release timing with IP holder Sony. We will make an announcement soon.
Could you confirm the combined revenue for Aion 2 in Korea and Taiwan?
CFO Won-june Hong = Combined Q3 revenue for Aion 2 across Korea, Taiwan, and global markets reached 52.6 billion won. Because most global revenue was deferred to Q4 in accordance with accounting policies, Q3 recognized global revenue was only 1.9 billion won.
Which new titles were assumed in the 2027 annual revenue guidance? How were revenue trajectories assumed for Aion 2 and existing games?
CFO Won-june Hong: You are likely curious about the composition of next year's guidance. Most importantly, revenue from Lineage Classic and Aion 2 will reflect full-year contributions next year. Both titles will serve as key revenue drivers in our core gaming business.
Next year, 10 new titles will be launched, primarily shooter and subculture games. For shooters, in-house developed Cinder City is representative, while subculture will feature various new releases led by Astraea Oratio launching early next year. Publishing the sequel to the Survivor.io IP, announced today, will also play a key role in revenue.
Lastly, we stated our confidence in achieving at least 55% growth in mobile casual compared to this year. Applying that to this year's annual revenue will yield an approximate figure. The 2027 revenue guidance of 3.2 to 3.4 trillion won is a conservative target that we feel most confident is achievable. We intend to work hard to beat it, just as we did this year. Revenue upside from Horizon and additional mobile casual M&A is not included in this figure.
What is the overall market size for JustPlay's sector? Does it compete directly with AppLovin, and where does its competitive advantage come from?
Co-CEO Byung-moo Park: Total Addressable Market (TAM) for the overall mobile advertising market is currently around $80 billion, of which the reward app market TAM accounts for about $3 billion to $4 billion. Based on various estimates, we project the overall mobile ad market to reach approximately $156 billion by 2030. The reward app market is estimated to reach around $9 billion to $12 billion, depending on projections.
While the reward app market is relatively young, it has grown more than twice as fast as the overall mobile ad market. We believe it will continue to grow at more than double the pace of the broader mobile ad market.
We plan to explain overall market conditions and our competitive edge in greater detail at our Media & Analyst Day early next year. Briefly speaking, however, the reward app market is developing into a complementary relationship with AppLovin rather than competing directly.
Traditional reward apps functioned primarily as conduits that acquired initial users and passed them to advertisers, but JustPlay owns its own games while fulfilling this role, enabling continuous tracking of user behavior. Consequently, user retention rises and MAUs accumulate, creating a virtuous cycle. We will share further details early next year once our framework is complete.
Could you share the timing or sequence of first-half releases? In terms of financial expectations, which games carry higher weight in the guidance?
Co-CEO Byung-moo Park: We expect Astraea Oratio to launch first in Q1. Following that, 1 to 2 new games will launch almost every month across Q1 and Q2. While there are third-party titles, we also have internally developed Cinder City, and personally, I hope Cinder City generates the strongest revenue.
Which metrics give you confidence in Astraea Oratio's potential success? How are player feedback improvements progressing?
Co-CEO Byung-moo Park: Detailed test metrics relate to development know-how so we cannot reveal everything. As one key indicator, Day 1 retention exceeded 90%. This was the top metric recorded in testing, giving us strong confidence. Naturally, CBT yielded various feedback, but adjustments like balance tuning and difficulty scaling can be addressed in a short timeframe, so we don't foresee major issues. We expect to share more at AGF in December.
Are there any ongoing M&A plans regarding core games?
Co-CEO Byung-moo Park: We have no M&A plans in core games for the time being.
What are the plans regarding shareholder return?
Co-CEO Byung-moo Park: For shareholder returns, we will adhere to disclosed principles of allocating 30% of net profit to cash dividends through 2027. However, to incorporate feedback and enhance corporate value, we are reviewing our overall shareholder return policy.
While this requires further discussion and board approval, personally I believe adopting Free Cash Flow (FCF) instead of net profit makes sense. Implementing a flexible shareholder return policy—prioritizing share repurchases and cancellations when share prices are depressed, and increasing dividends when share prices rise—would be appropriate. We will finalize and announce the company's official stance before the next general shareholders' meeting.
We cannot disclose immediate share buyback or cancellation plans at this time. Uncertainties remain as several strategic initiatives are currently underway. We believe it is appropriate to clarify our position after these uncertainties are resolved, so we cannot announce immediate buyback or cancellation plans today.