Date/Time: November 11, 2026 (Wed) at 16:00
Attendees: Co-CEO Byung-moo Park, CFO Won-june Hong, Head of Mobile Casual Center Anel Ceman
Agenda: NC Q3 2026 Earnings Results and Future Strategy
■ Summary of NC Q3 2026 Earnings Results and Status
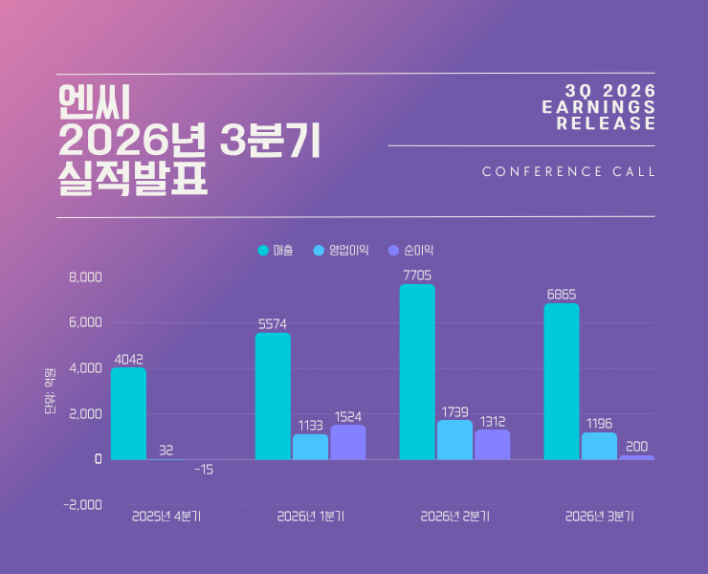
▣ Q3 2026 Earnings Summary
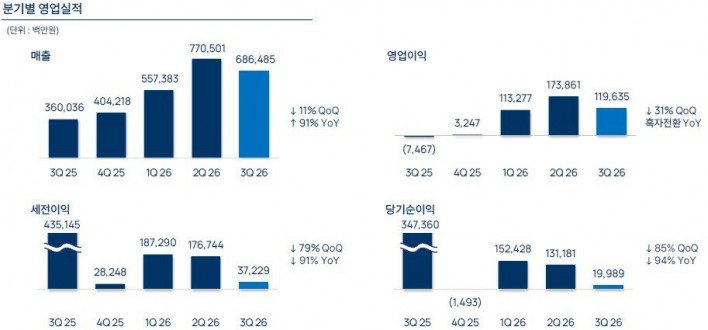
- Q3 2026 revenue of 686.5 billion won (+91% YoY, -11% QoQ)
- Operating profit of 119.6 billion won (turned profitable YoY, -31% QoQ)
- Pre-tax profit of 37.2 billion won (-91% YoY, -79% QoQ)
- Net profit of 20.0 billion won (-94% YoY, -85% QoQ)
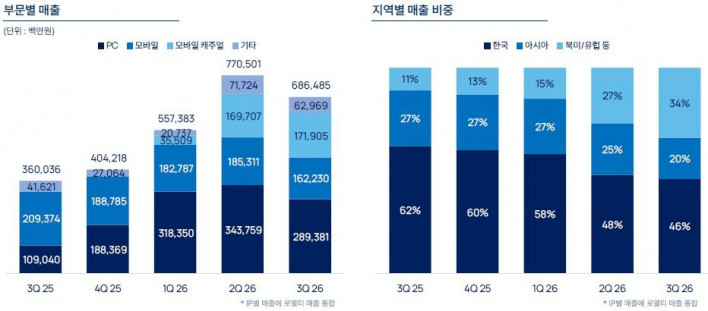
- Mobile revenue of 162.2 billion won
- PC revenue of 289.4 billion won, down 16% QoQ
└ Up 165% YoY
- Mobile casual revenue of 171.9 billion won
└ Accounting for 25% of total quarterly revenue
└ Growth driven by JustPlay's user expansion and advertiser demand
- Revenue breakdown by region: Korea 46%, Asia 20%, North America/Europe, etc. 34%
└ Overseas revenue accounted for 54%
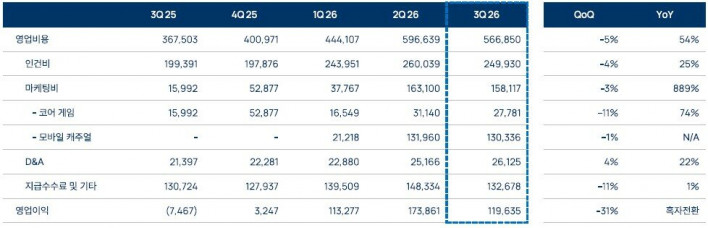
▣ Q3 2026 Operating Expenses Summary
- Q3 2026 operating expenses of 566.9 billion won (+54% YoY, -5% QoQ)
└ Labor costs of 249.9 billion won (+25% YoY, -4% QoQ)
└ Marketing expenses of 158.1 billion won (+889% YoY, -3% QoQ)
└ Depreciation and amortization of 26.1 billion won (+22% YoY, +4% QoQ)
└ Royalty fees and other expenses of 132.7 billion won (+1% YoY, -11% QoQ)
▣ Co-CEO Byung-moo Park's Statement
2026 can be described as a year where our three core growth pillars established their foundation and delivered tangible results. First, we demonstrated successful launches of both legacy and new IPs in Korea and Taiwan in Q1. In Q2, we showed the results of acquiring JustPlay, a core pillar of our Mobile Casual Division, and in Q3, we successfully executed in-house global publishing for our new IP, Aion 2.
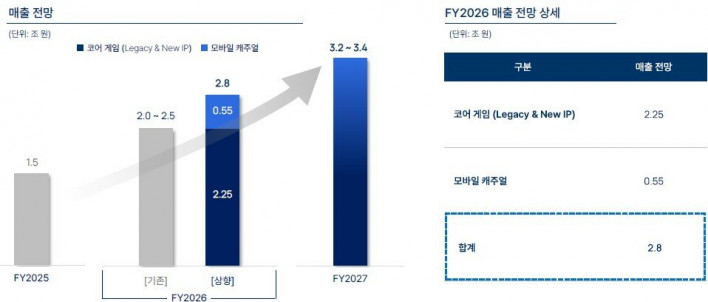
Last year, we provided full-year 2026 revenue guidance of 2 trillion to 2.5 trillion won, but based on current trends, we expect to significantly exceed this by achieving 2.8 trillion won in annual revenue. Compared to 2025 revenue of around 1.5 trillion won, this represents remarkable growth, made possible thanks to the interest and advice of our customers and shareholders, as well as the dedicated efforts of our employees.
Next year, in 2027, we expect continued growth as these three core growth pillars become fully established and refined. Accordingly, we have announced a 2027 revenue guidance of 3.2 trillion to 3.4 trillion won. Despite setting this revenue guidance, we will make every effort to exceed it, just as we did this year.
To ensure the visibility of this forecast, three key areas warrant attention. For legacy IPs, we will continuously pursue the refinement of live services while expanding into new regions and launching spin-offs—such as the global launch of Aion Mobile, the China release of Lineage Mobile, and the release of Mistbound utilizing the Guild Wars IP—to sustain solid revenue.
For new IPs, as demonstrated with Aion 2, we will further refine our established global publishing capabilities. Following improvements made through user testing, new shooter and subculture games that we have been preparing—such as Astraea Oratio, Cinder City, Limit Zero Breakers, and Time Takers—will be launched sequentially throughout the first half of next year.
In the mobile casual segment, through additional acquisitions and business expansion in Q4, we expect the framework for reward platforms and publishing services within the mobile casual sector to be largely completed. From next year onward, we will enhance these synergies to achieve quantum growth.
Finally, while we are expanding the application of AI capabilities to game development to match the rapidly changing AI environment, I would like to emphasize that NC's business structure transformation is being optimized for and refined alongside these recent paradigm shifts in AI. First and foremost, MMO games—NC's core strength—are considered a field that is difficult to replace with AI for a considerable time due to massive game content, sophisticated server technology, and continuous live service operations, so we will continue to develop and refine them.
Furthermore, in a reality where numerous games are recently being developed using AI, strengthening publishing capabilities becomes even more critical. To this end, strengthening global publishing capabilities for co-op games and turning the mobile casual segment into a publishing platform constitute a business structure that can drive continuous growth in an AI-driven environment.
While I focused today on our 2027 guidance, based on the refinement of NC's business structure, full-year contributions from major AAA IPs, and the completion of the Mobile Casual Division framework in 2028, we expect to see explosive growth once again. We will continue to communicate further details through future media events and other channels.
■ Q&A
After Aion 2's global release, the objective metric visible externally is Steam traffic, which shows a similar trend compared to Throne and Liberty's global launch. Retention does not seem noticeably better. Is this due to the limitations of MMORPGs, or are there business model (BM) issues? Please share your thoughts.
Co-CEO Byung-moo Park: I acknowledge that Korean MMORPGs generally exhibit similar user churn rates due to their vertical progression structures. However, there is a difference in the market environment compared to TL. While there were not many competing titles when TL launched, that was not the case for Aion 2. I would first like to emphasize that this performance was achieved in an environment where competitors like Call of Duty, Phantom Blade Zero, and World of Warcraft Forever were continuously being released.
Furthermore, when comparing TL and Aion 2, retention rates for paying users and hardcore players are significantly higher for Aion 2. We are continuously monitoring this as well, and we would appreciate it if you keep observing through November and December.
Mobile casual growth is very strong. What factors are driving this high growth? To what extent is mobile casual reflected in next year's guidance?
Co-CEO Byung-moo Park: JustPlay's sustained explosive growth can be viewed from two aspects. First, from a macro perspective, platforms are currently significantly driving game development. While around 2,000 mobile casual games were released per month last year, about 4,000 to 5,000 are being released per month this year. This provides the macro backdrop that enables reward apps like JustPlay to continuously grow alongside industry growth.
From a micro perspective, the team consists of talent highly specialized in AppLovin's adtech. They structure products to be user-friendly, which leads to higher user acquisition (UA) and increases monthly active users (MAU). Consequently, a virtuous cycle is expanding as advertisers participate by paying higher ad rates.
This virtuous cycle is well established on a micro level, and it will continue to drive growth. Lastly, we expect the combined revenue of reward apps, publishing, and mobile casual game studios to account for approximately 25% to 30% of next year's guidance.
CFO Won-june Hong: Inorganic growth is not included. Additional revenue and growth resulting from newly announced M&A deals are not factored into this guidance.
Are there plans for UI/UX updates in mobile casual? Could you also provide an update on key metrics for JustPlay?
Co-CEO Byung-moo Park: JustPlay's main markets are currently North America and parts of Europe. I recently saw that the JustPlay app is available in Korea, but that is a beta service rather than a formal launch. Once we officially enter the Korean market in the future, we will naturally address areas that require improvement.
As mentioned earlier, our envisioned framework will be completed through additional M&A and business expansion. This includes plans to expand reward apps into 3P and IAP domains. Once expanded into 3P and IAP, the triangular synergy among studios, publishing, and reward apps will be further enhanced alongside the existing 1P model.
CFO Won-june Hong: One of the key mobile casual business strategies envisioned by our co-CEOs is the additional M&A currently underway. JustPlay focuses primarily on IAA and 1P, whereas the additional business we are pursuing focuses on IAP and 3P. Thus, the strategy is to establish a complete system through complementary relations.
Detailed metrics for JustPlay are tied to core competitiveness, so it is difficult to share specifics. However, you can consider that MAU has roughly doubled compared to last year. Based on current trends, we expect 2027 revenue to grow by at least an additional 50% compared to this year's expected annual revenue. We feel confident based on our current metrics.
What is the marketing expense guidance for 2027?
CFO Won-june Hong: We managed marketing expenses very efficiently this year. We have operated marketing expenses efficiently over the past three years, and with the introduction of ROAS concepts in our mobile casual business, management has become even more systematic.
As we have consistently stated, we strictly maintain the principle of keeping marketing expenses under 10% of total revenue. Next year, despite multiple new game launches, we expect marketing spend to remain meaningfully below 10% of total revenue.
What are the plans for Horizon Steel Frontiers?
Co-CEO Byung-moo Park: Horizon Steel Frontiers is nearing completion, and we are continuously discussing the release timing with IP holder Sony. We will make an announcement soon.
Could you confirm the combined Q3 revenue for Aion 2 in Korea and Taiwan?
= Combined Q3 revenue for Aion 2 across Korea, Taiwan, and global markets was 52.6 billion won. Most global revenue was deferred to Q4 in accordance with accounting policies, so global revenue recognized in Q3 was only 1.9 billion won.
What new titles were assumed in the 2027 annual revenue guidance? How did you project revenue trends for Aion 2 and legacy games?
CFO Won-june Hong: You may be curious about the composition of next year's guidance. The most important point is that revenue from Lineage Classic and Aion 2 will be reflected for a full year next year. Both titles will serve as major revenue drivers for our existing core game business.
Next year, 10 new titles will launch, primarily shooter and subculture games. For shooters, our internally developed Cinder City is a key title, while subculture will feature various new games centered around Astraea Oratio, scheduled to launch early next year. Publishing the sequel to the Survivor.io IP, announced today, will also play a meaningful role in revenue.
Lastly, I mentioned that we are confident of at least 55% growth in the mobile casual business compared to this year. Applying that to this year's annual revenue will give a rough idea of the figure. The 2027 revenue guidance of 3.2 trillion to 3.4 trillion won is a conservative number that we feel most confident about achieving. As with this year, we will work harder to surpass it. This figure does not include potential revenue increases from Horizon or additional mobile casual M&A.
What is the total market size for the industry JustPlay operates in? Do you compete directly with AppLovin, and where does your competitive advantage come from?
Co-CEO Byung-moo Park: Currently, the TAM for the total mobile advertising market is around $80 billion, within which the reward app TAM is approximately $3 billion to $4 billion. Based on various data sources, we project the total mobile advertising market to reach around $156 billion by 2030. Depending on estimates, we expect the reward app market to reach around $9 billion to $12 billion.
Although the reward app market is relatively young, it has grown more than twice as fast as the overall mobile advertising market so far. We expect it to continue growing at more than double the pace of the overall mobile ad market going forward.
We plan to explain the overall market situation and our competitive edge in greater detail at a Media and Analyst Day early next year. Briefly speaking, however, the reward app market is developing into a complementary relationship rather than directly competing with AppLovin.
While traditional reward apps served as conduits that acquired users initially and passed them to advertisers, JustPlay operates with its own first-party titles, allowing us to continuously track user behavior. Consequently, user retention rates increase and MAUs accumulate, creating a virtuous cycle. We will share further details early next year once our framework is completed.
Can you share the timing or order of H1 launches? In terms of financial expectations, which games are projected with higher expectations in guidance?
Co-CEO Byung-moo Park: We expect Astraea Oratio to launch first in Q1. Following that, the schedule calls for launching one or two new titles almost every month across Q1 and Q2. While there are third-party titles, since we are internally developing Cinder City, I personally hope Cinder City yields the highest revenue.
Regarding Astraea Oratio, what metrics make you confident in its success? How are you addressing user feedback?
Co-CEO Byung-moo Park: Test metrics involve development know-how, so it is difficult to disclose everything. Symbolically speaking, Day 1 retention rate exceeded 90%. As this represents a top-tier test metric, we feel very confident. While we received various feedback from the CBT, issues like balance tuning and difficulty adjustments can be addressed in a short time frame, so we do not see them as major obstacles. We expect to know more clearly around AGF in December.
Are there any ongoing M&A plans for the core game business?
Co-CEO Byung-moo Park: We have no M&A plans for core games for the time being.
What are the plans regarding shareholder returns?
Co-CEO Byung-moo Park: For shareholder returns, we will uphold our disclosed principle of paying 30% of net profit as cash dividends through 2027. However, to incorporate feedback and enhance corporate value, we are reviewing our overall shareholder return policy.
While further discussion and board approval are required, personally, I believe introducing the concept of Free Cash Flow (FCF) instead of net profit is appropriate. When the stock price is low, adopting share buybacks and cancellations as a principle, and increasing dividends when the stock price rises, creates a flexible shareholder return policy. We will finalize and announce the company's official position on this ahead of the next general shareholders' meeting.
We cannot disclose immediate plans for share buybacks and cancellations. Strategic initiatives currently underway carry remaining uncertainties. Because we believe it is appropriate to clarify our position after these uncertainties are resolved, it is difficult to announce immediate share buyback or cancellation plans.