Date & Time: Tuesday, November 10, 2026 at 17:00
Attendees: Chairman Patrick Söderlund, CEO Junghun Lee, CFO Shiro Uemura
Presentation Content: Nexon Q3 2026 Financial Results and Future Strategy
■ Summary of Nexon's Q3 2026 Financial Results and Current Status
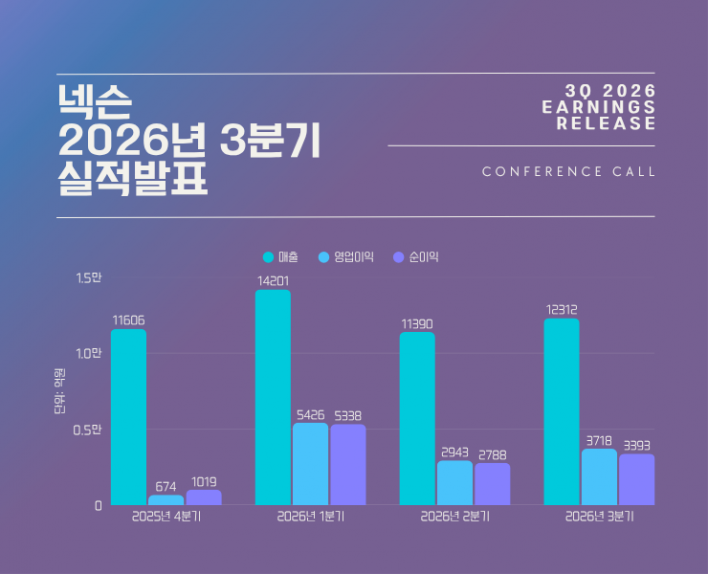
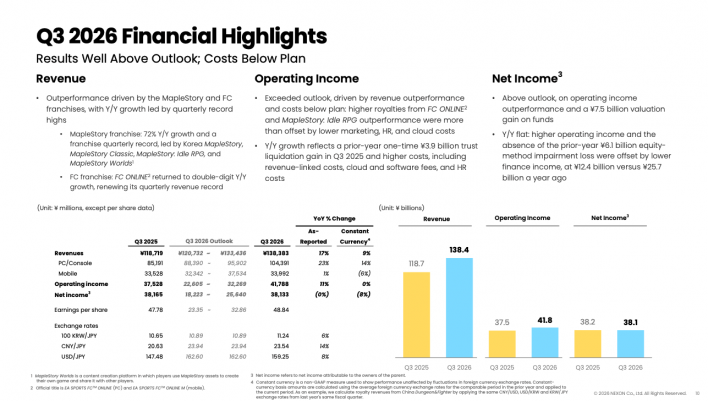
▣ Summary of Q3 2026 Results (Applied FX Rate: 11.24 JPY per 100 KRW)
- Q3 2026 Revenue: 1.2312 trillion won (+17% YoY, +14% QoQ)
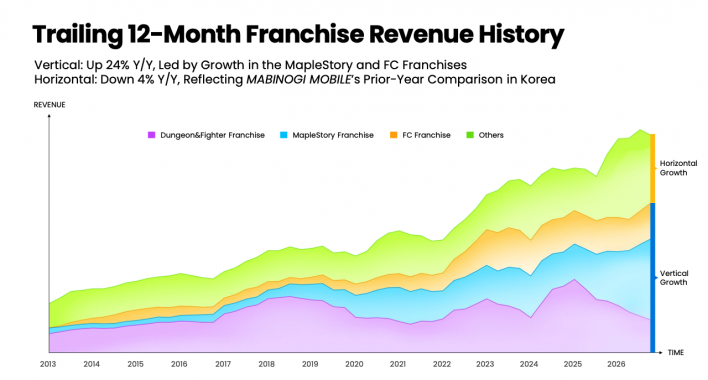
└ 'MapleStory' franchise revenue increased 72% YoY, setting an all-time quarterly high record
└ Domestic PC 'MapleStory' revenue grew 19%, while China PC 'MapleStory' revenue grew nearly fourfold driven by the success of 'MapleStory Classic' in China
└ Continued growth of 'MapleStory Worlds' and revenue contribution from 'MapleStory: Idle RPG'
└ 'FC' franchise recorded double-digit YoY growth, with 'FC Online' setting an all-time quarterly revenue record
└ Steady revenue contribution from 'ARC Raiders', surpassing 17 million cumulative global sales
└ On the other hand, 'Dungeon & Fighter' franchise revenue declined 33% YoY, and domestic revenue for 'Mabinogi Mobile' also decreased YoY
└ By region, revenue increased 17% in Korea, 41% in North America & Europe, and 77% in other regions, while decreasing 7% in China and 13% in Japan
- Q3 2026 Operating Income: 371.8 billion won (+12% YoY, +34% QoQ)
└ Exceeded company guidance due to higher-than-expected revenue from 'MapleStory' and 'FC' franchises, alongside cost savings in marketing, labor, and cloud infrastructure
└ Royalty expenses increased in line with revenue growth from 'FC Online' and 'MapleStory: Idle RPG'
└ Payment processing fees and creator payouts related to 'MapleStory: Idle RPG' and 'MapleStory Worlds' increased
└ Marketing expenses increased due to user acquisition for 'MapleStory: Idle RPG' and promotional activities for 'ARC Raiders' and 'Mabinogi Mobile'
└ Labor costs rose YoY due to a one-time stock option adjustment related to a special dividend and headcount growth
└ Cloud and software service costs also grew, though actual spend remained lower than originally planned
- Q3 2026 Net Income: 339.3 billion won (flat YoY, +29% QoQ)
└ Net income beat expectations as operating income exceeded guidance and a fund valuation gain of 7.5 billion yen was recognized
└ No equity-method investment impairment losses occurred this year, compared to 6.1 billion yen recorded in Q3 2025
└ However, finance income decreased from 25.7 billion yen YoY to 12.4 billion yen, keeping net income at a similar level to the prior-year period
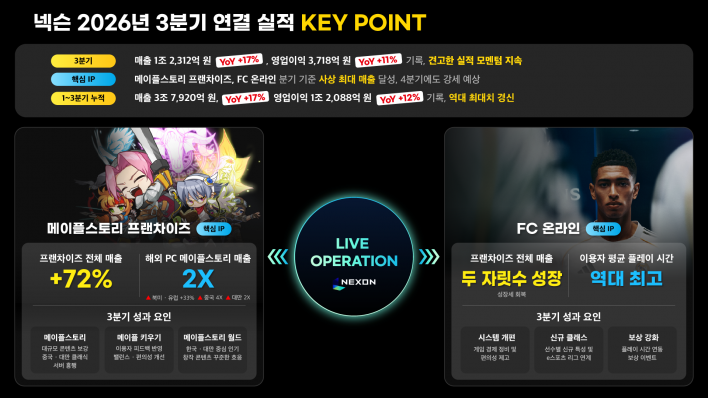
▣ Cumulative YTD 2026 Results (Applied Average FX Rate: 921.1 KRW per 100 JPY for Q1–Q3)
- Cumulative Revenue: 3.792 trillion won (+17% YoY)
- Cumulative Operating Income: 1.2088 trillion won (+12% YoY)
- Cumulative Net Income: 1.1513 trillion won (+54% YoY)
└ Record-high YTD Q1–Q3 performance across revenue, operating income, and net income
└ Growth of the 'MapleStory' franchise and global success of 'ARC Raiders' contributed to cumulative performance
▣ Q4 2026 Financial Outlook (Applied FX Rate Expectation: 846.7 KRW per 100 JPY)
- Expected Revenue: 912.2 billion won to 1.0067 trillion won (-13% to -4% YoY)
└ 'MapleStory' franchise projected to grow approximately 70% YoY; 'FC' franchise expected to maintain double-digit growth rate
└ Reflects high base comparison effects from the release of 'ARC Raiders' in Q4 2025 and lower revenue from the 'Dungeon & Fighter' franchise
└ Revenue contribution expected from the Japanese service of 'Mabinogi Mobile' and new titles launching in November
- Expected Operating Income: 34 billion won to 99.1 billion won
└ Expecting YoY reductions in labor costs, marketing expenses, and payment processing fees
└ Royalty expenses expected to expand due to growth in the 'FC' franchise and new publishing titles
└ Cloud/software service costs and creator payouts for 'MapleStory Worlds' projected to increase
- Expected Net Income: 39.4 billion won to 89.9 billion won
└ Projected to decrease YoY due to a high base effect from 16.6 billion yen in FX and securities valuation gains recognized in Q4 2025
▣ Upcoming Pipeline
- 'Mabinogi Mobile' launched service in Japan this past October
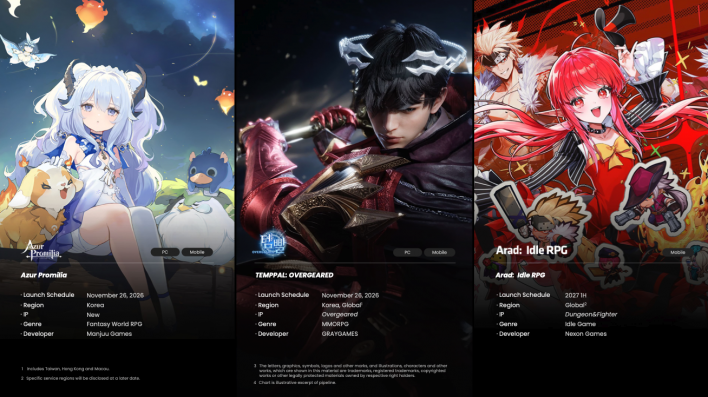
- 'Overgeared' scheduled to launch on November 26 in Korea, Taiwan, Hong Kong, and Macao
└ PC/Mobile MMORPG developed by Grey Games
- 'Azur Promilia' scheduled to launch domestically on November 26
└ PC/Mobile fantasy world RPG developed by Manjuu Games
- 'Dungeon & Fighter Idle' launch schedule pushed to H1 2027 to polish overall quality and user experience
└ Mobile idle game under development by Nexon Games, representing the first step in expanding the 'Dungeon & Fighter' franchise
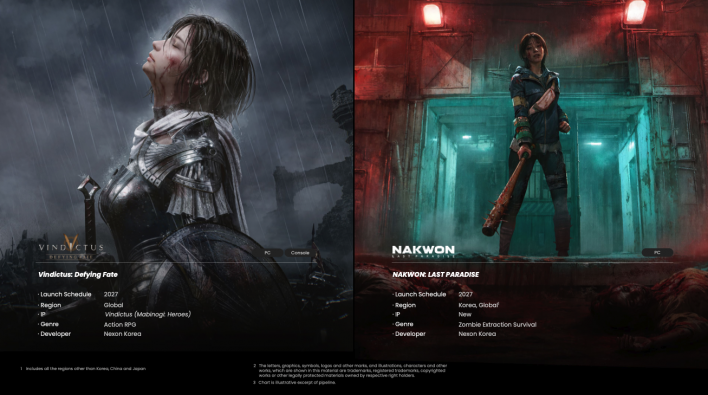
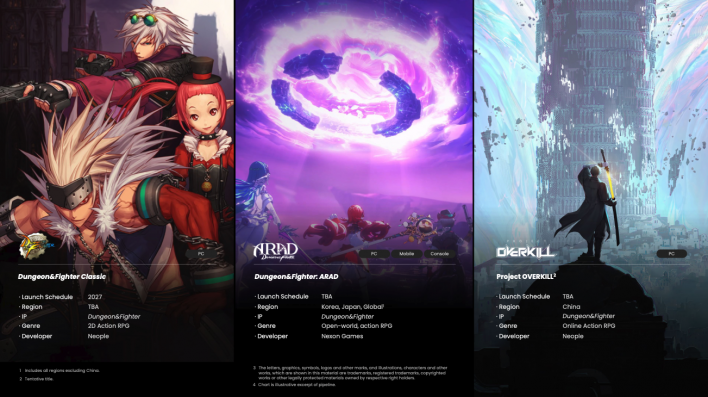
- Plans to launch 'Dungeon & Fighter Classic', 'Vindictus: Defying Fate', and 'Nakwon: Last Paradise' in 2027
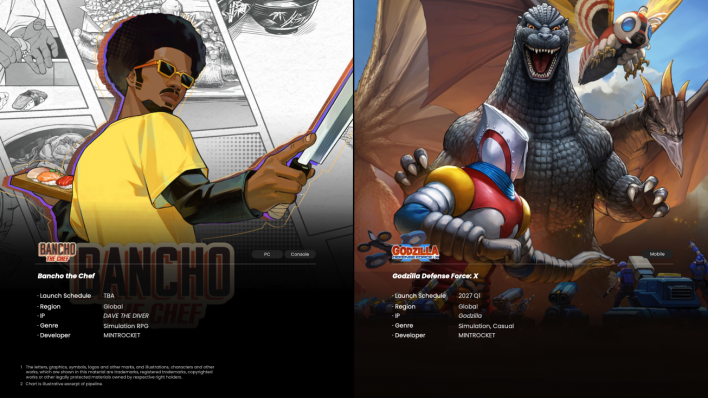
- Mintrocket's 'Godzilla Defense Force X' scheduled for release in Q1 2027
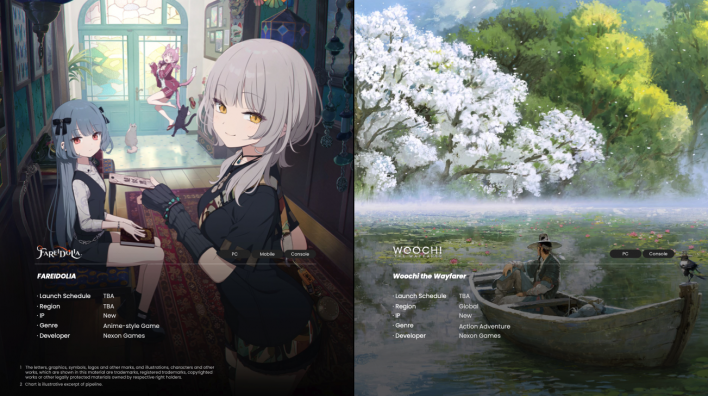
- Titles including 'Dungeon & Fighter: Arad', 'Project Overkill', 'Pareidolia', and 'Woochi the Wayfarer' are also under active development
└ Specific release schedules for these titles will be disclosed at a later date
▣ Development and Cost Efficiency Strategy
- Established performance goals per new project and introduced a phased development approval process
└ Cancelled 6 existing projects to concentrate development resources on projects with high commercial viability
└ Reallocated budget and development staff from those projects to initiatives with higher commercial growth potential
└ Managed overall headcount below plan, staying flat with the prior-year period
└ Accelerating AI technology adoption while maintaining the stance that core creative decision-making remains with development personnel
■ Q&A Session
Q. The slump in the Dungeon & Fighter franchise is persisting. Is user churn caused by game aging, or are there other factors? In the past, the franchise successfully bounced back whenever performance dipped, but recent recovery seems challenging. What is management's assessment of the current situation and future strategy?
Junghun Lee, CEO = First, let me answer regarding the Dungeon & Fighter franchise. For PC Dungeon & Fighter, we were aiming for a rebound through major seasonal updates and ongoing live operations, but the season that launched last April did not resonate well with players, resulting in continued weakness. Currently, we are focusing all our efforts on the next seasonal update scheduled for early next year.
For mobile as well, even though we transferred part of the development work to Tencent and have been delivering various content updates much faster than before, those efforts have not yet directly reflected in financial results.
To address the severity of this recent situation, top executives from Tencent and Nexon, along with all key organizations related to the franchise, gathered for an in-depth workshop. There, we discussed the long-term live service direction for PC and Mobile Dungeon & Fighter in China.
The most important outcome was establishing structural changes and concrete execution plans to optimize live operations. Previously, we relied heavily on major updates 1–2 times a year, but going forward, we plan to expand content output itself and gradually increase the volume of content provided to players starting next year.
We also plan to improve community management policies and change how the development team communicates with players. We believe we will be able to share specific details of these changes at the Dungeon & Fighter player event taking place in China on November 20.
Above all, both Nexon and Tencent agree that Dungeon & Fighter possesses a unique brand, to the point of being considered its own distinct genre in the Chinese market. We believe there is no competitor in the market today that matches the action RPG gameplay built by Dungeon & Fighter. Both management teams shared the view that while many competitors tried to capture Dungeon & Fighter's market share over the years, none succeeded.
Moving forward, we will push for a rebound in existing PC and mobile live services while simultaneously executing our franchise expansion strategy. We plan to expand the value of the IP through various titles, including Dungeon & Fighter Classic, aimed for launch in China next year, and Project Overkill, a new title revealed for the first time during this earnings release.
Q. Multiple new titles are scheduled for release in 2027. Which titles does the company evaluate as having the highest potential for major success? In particular, do you expect the new Dungeon & Fighter titles launching in China to drive a financial rebound for the franchise?
Junghun Lee, CEO = First, I'd like to mention that our 2027 release lineup is structured much more broadly and diversely than in 2026.
We are preparing Nakwon: Last Paradise, a completely new IP, alongside Vindictus: Defying Fate expanding the Mabinogi Heroes IP, as well as Dungeon & Fighter Idle and Dungeon & Fighter Classic utilizing the Dungeon & Fighter IP.
Additionally, we plan to expand service for MapleStory: Idle RPG into new regions. It will be a year where both existing IP expansions and new IP launches take place simultaneously.
We expect this to be a year where such diverse strategies and new titles translate into tangible results. We look forward to introducing the titles in development to players, and we ask for your continued interest and support.
Q. The MapleStory franchise continues to demonstrate strong performance. Do you expect this growth momentum to continue into 2027? With additional growth expected in Q4 from collaborative content, do you have room to expand user engagement next year, or do you expect growth to stabilize while other franchises contribute more?
Junghun Lee, CEO = First, I hope investors take note of the performance demonstrated by various businesses within the MapleStory franchise in Q3. In particular, MapleStory Classic performed significantly better than internal projections.
To state the conclusion upfront, we expect the growth momentum centered around MapleStory Classic and MapleStory Worlds in the second half of this year to remain solid in 2027 as well.
Let me explain each business within the franchise. First, for PC MapleStory's live service, we are preparing plans to consistently deliver high-quality content updates, similar to this year. Through this, we aim to stably maintain user engagement.
MapleStory Classic is also in its early stage, having recently launched services in China, Taiwan, and Western markets. Given the strong reception it is currently receiving, we plan to actively expand content supply to sustain initial momentum.
MapleStory Worlds is a UGC platform where users create content themselves. Our top priority right now is solidifying its service foundation. We recently hosted a global developer competition and are planning an open beta in Korea for MapleStory Worlds 2.0, which includes webtoon creation features.
Finally, for MapleStory: Idle RPG, following its Korean launch, we are managing user retention stably while preparing to expand service into additional regions.
At this point, we have no new MapleStory titles to announce for 2027. However, with multiple businesses in the existing franchise delivering strong results, we expect to maintain solid growth next year comparable to this year.
Q. Nexon is actively expanding its use of AI. Utilizing 30 years of accumulated contextual capital in live services and broadening AI application across various games will likely increase costs. On the other hand, you can expect revenue gains and improved user retention. How do you evaluate the cost and revenue impact of AI adoption? Do you expect tangible revenue contributions within the next 1–2 years, or should we expect them from a medium-to-long-term perspective of 3–5 years?
Patrick Söderlund, Chairman = As other companies are likely experiencing similar shifts, it is clear that AI and new tools are bringing substantial efficiency gains.
When utilizing AI, Nexon focuses on repetitive tasks within the game creation process. Offloading these tasks to AI allows developers to focus on more creative work. It also makes the process of testing bold, new ideas faster and less expensive.
However, the actual output inside the games remains the creation of the people making them, as the gaming industry is fundamentally driven by creativity.
We are already seeing concrete results in our live service titles. For instance, using AI to convert artwork created by designers into pixel art sped up production speed by more than 10x. This enabled us to produce far more art assets required for games like MapleStory and Dungeon & Fighter.
We are also utilizing AI for hyper-localization to tailor games to regional cultures and player characteristics. This allows us to localize several times faster than before while maintaining the quality required for local cultures.
Of course, using and refining AI involves costs as well. Therefore, related investments are conducted cautiously and in phases, measuring outcomes at each stage before committing larger investments.
Our goal is not to use AI to make games with fewer people. Our goal is to make better games with the development talent we currently have.
Q. What was the background behind Q3 marketing expenses being spent lower than originally planned? With marketing and promotion expenses expected to expand in Q4, what criteria will you apply when deciding actual spend?
Shiro Uemura, CFO = Our Q3 marketing budget was planned primarily around new titles. While marketing for existing IPs is necessary, we generally allocate a larger proportion to new titles.
When conducting marketing, our goal is to execute in the most efficient and effective manner possible.
However, in Q3, some scheduled marketing activities experienced timeline shifts. That was the main background for marketing expenses coming in lower than originally planned.
Accordingly, we plan to more aggressively pursue the marketing and promotional activities in Q4 that could not be conducted during Q3.
Q. After the 'Frozen Mountain Pass' update for ARC Raiders, returning users surged concurrent player counts, but they dropped off quickly afterward. Looking at the Q4 forecast, there seems to be a recognized limit to acquiring new users. Do you plan to focus on boosting engagement and revenue from existing users rather than expanding the user base going forward?
Patrick Söderlund, Chairman = Based on our experience and comprehensive analysis of data from competing games with similar genres and business models, we believe that delivering two high-quality, large-scale updates per year is an appropriate cadence to retain existing core players while driving new sales.
First, we believe the 'Frozen Mountain Pass' update has performed remarkably in line with our expectations so far.
Following the update in October, it received a strong reception from players, and subsequent in-game activity and sales figures have been gradually normalizing.
Going forward, we plan to continually grow our player community through various events and promotions.
As mentioned earlier, we maintain our policy of providing at least two major content updates per year for ARC Raiders and will continue to execute on that plan.
Q. I would like to clarify further. Moving forward, to expand ARC Raiders' revenue, will you focus on acquiring new paying users, or on encouraging additional purchases from existing users?
Patrick Söderlund, Chairman = ARC Raiders is a paid premium game, so all players currently playing have already purchased the game as paying users.
Naturally, we intend to pursue both directions. We must incentivize new players to purchase the game while simultaneously giving existing players ample reasons to keep playing.
We also believe it is important to enable existing players to continue purchasing various in-game items. We will simultaneously drive new user acquisition, existing user retention, and additional in-game purchases.
Q. MapleStory Classic contributed significantly to this quarter's results. Does management view this as a new business pillar capable of generating sustained revenue beyond 2027, or as a temporary nostalgia effect? How do you plan to manage update cadences between original MapleStory and Classic, and how will you resolve user overlap or cannibalization concerns while growing both services simultaneously?
Junghun Lee, CEO = As mentioned earlier, MapleStory Classic received a much stronger response in Taiwan, China, and Western markets than initially anticipated internally.
In particular, performance in Taiwan and China was a key factor in our strong Q3 results. In those markets, user inflows reached up to 9 times higher compared to existing live services. Furthermore, cannibalization between Classic and existing live services was very minimal.
In Q4, we are actively expanding service in Western markets as well, where initial local reception has also been positive. To sustain this early momentum, we are focusing on strengthening Classic content updates and maintaining player engagement.
Finally, beyond Classic itself, I would like to explain how Nexon views the 'Classic Playbook' across the entire company.
As you know, Nexon holds a large portfolio of PC online games that have maintained live operations for over 20 years, including Dungeon & Fighter, MapleStory, and Mabinogi. These games continue to run successful live services today.
From the perspective of a company holding numerous IPs with such long histories, the Classic Playbook is a useful strategy that can be applied in various ways.
Over the past two decades, millions of players have created accounts and played these games. Every player holds different memories of their most cherished eras and experiences within each game.
Therefore, Nexon does not pursue a one-size-fits-all application of Classic services for every game. We plan to strategically adapt and leverage the Classic Playbook according to the specific experiences of each IP and its players, and we already have plans in place for this.
Q. Could you explain the Q4 cost structure compared to the previous quarter based on the financial outlook? Revenue is expected to decline by approximately 20–30 billion yen compared to Q3, but combined costs (COGS + SG&A) appear to increase by about 10.5 billion yen. Why are costs increasing even as revenue declines? Is it due to labor or other expenses? We would like to know the specific cost drivers.
Shiro Uemura, CFO = Quarterly costs can increase or decrease depending on revenue scale and composition.
Comparing Q3 and Q4, the single largest factor driving the cost increase is marketing expense. As mentioned earlier, some marketing activities originally scheduled for Q3 were postponed, and those expenses will be executed in Q4. That is the primary factor.
Another factor is payment processing fees (PG fees). Payment fees naturally fluctuate based on revenue changes in individual titles. In particular, if FC Online maintains its current revenue growth momentum, associated payment processing fees are expected to rise accordingly.
Junghun Lee, CEO = I would like to add one more perspective. We hope investors pay special attention to the fact that Nexon's revenue mix itself is undergoing a shift.
Historically, China Dungeon & Fighter possessed a highly profitable business structure, but revenue from this business is currently expected to decrease YoY.
On the other hand, existing services expected to drive Q4 growth—such as the FC franchise, MapleStory: Idle RPG, and MapleStory Worlds—as well as Q4 releases like Overgeared, Azur Promilia, and Mabinogi Mobile in Japan, have different cost structures compared to China Dungeon & Fighter.
These titles and services incur revenue-linked costs, such as royalties and creator fees, directly proportional to their revenue scale.
Therefore, rather than looking solely at top-line revenue fluctuations, we ask that you also examine which titles are generating revenue and how the overall revenue composition is changing.